January 2025
Intermediate to advanced
416 pages
10h 30m
English
This chapter introduces the core concepts of modern financial markets and how they’re represented in QuantConnect. We’ll cover the modern US markets, data feeds, and the asset classes used in later chapters. Readers who are familiar with QuantConnect may skip this chapter.
The United States has 11 major stock exchanges. The two largest are the New York Stock Exchange (NYSE) and the National Association of Securities Dealers Automated Quotations System (NASDAQ). Trades on these exchanges are compiled by the Securities Information Processor (SIP) into a single data feed. This feed helps the Securities and Exchange Commission (SEC) determine the national best bid or offer (NBBO), which shows the best prices posted on public markets in the United States. When a new quote for more than 100 shares offers a better price, it is flagged as the NBBO. Quotes or trades involving fewer than 100 shares, known as odd lots, are excluded from this pricing. Figure 1.1 illustrates this flow.
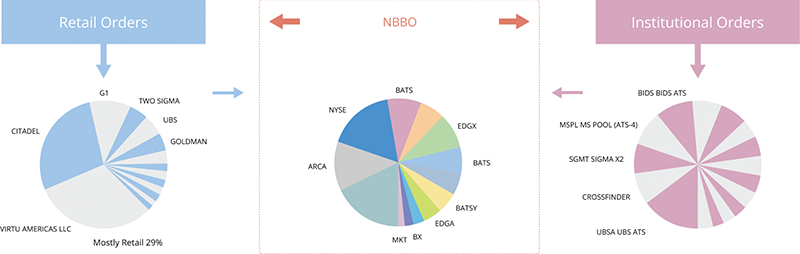
Figure 1.1 Flow of retail and institutional traffic across public and private markets, and the origin of national best pricing.
Brokerages often send orders to market makers to be executed “off the market.” Market makers executing these orders are required to provide fills within the NBBO price range. Furthermore, these off-market trades are reported ...
Read now
Unlock full access


 O’Reilly covers everything we've got, with content to help us build a world-class technology community, upgrade the capabilities and competencies of our teams, and improve overall team performance as well as their engagement.I wanted to learn C and C++, but it didn't click for me until I picked up an O'Reilly book. When I went on the O’Reilly platform, I was astonished to find all the books there, plus live events and sandboxes so you could play around with the technology.I’ve been on the O’Reilly platform for more than eight years. I use a couple of learning platforms, but I'm on O'Reilly more than anybody else. When you're there, you start learning. I'm never disappointed.I'm always learning. So when I got on to O'Reilly, I was like a kid in a candy store. There are playlists. There are answers. There's on-demand training. It's worth its weight in gold, in terms of what it allows me to do.