May 2011
Beginner to intermediate
384 pages
12h 28m
English
In the previous section, I demonstrated how to construct a market-level news sentiment index that can be used to predict the future direction of the S&P 500. Here, I will focus on constructing market-neutral strategies taking long and short positions in the top- and bottom-ranked industries, respectively. Being able to successfully rank industries based on sentiment should enhance the performance of a strategy, since more targeted investments can be made towards expected outperformers and underperformers during periods with long and short exposures, respectively.
Table 5.1. Performance statistics covering the out-of-sample period May 2005 through December 2009 for the strategies based on the Market-Level Sentiment Index (column 3) with an Event Novelty Score filter (ENS = 100), the Market-Level Sentiment Index (column 4) without an Event Novelty Score filter, and the 1-month price momentum strategy based on the S&P 500 (column 5). Pre-October and Post-October refer to the market high in October 2007
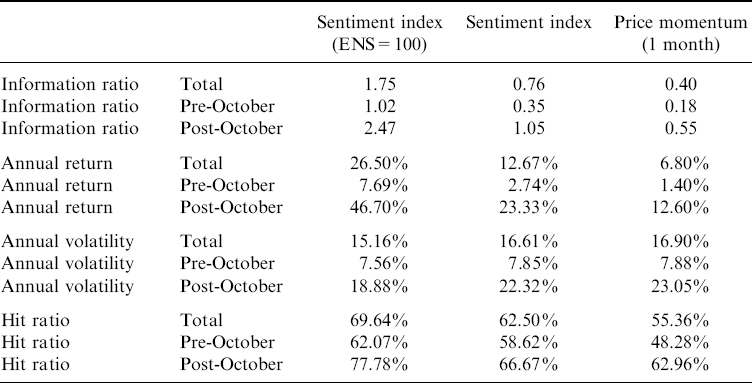
Table 5.2. Yearly annualized return covering the out-of-sample period May 2005 through December 2009 for strategies based on the Market-Level Sentiment Index (column 2) with an Event Novelty Score filter (ENS=100), the Market-Level Sentiment Index (column 3) without an Event Novelty Score filter, and the 1-month price momentum strategy based on the S&P 500 ...
Read now
Unlock full access


 O’Reilly covers everything we've got, with content to help us build a world-class technology community, upgrade the capabilities and competencies of our teams, and improve overall team performance as well as their engagement.I wanted to learn C and C++, but it didn't click for me until I picked up an O'Reilly book. When I went on the O’Reilly platform, I was astonished to find all the books there, plus live events and sandboxes so you could play around with the technology.I’ve been on the O’Reilly platform for more than eight years. I use a couple of learning platforms, but I'm on O'Reilly more than anybody else. When you're there, you start learning. I'm never disappointed.I'm always learning. So when I got on to O'Reilly, I was like a kid in a candy store. There are playlists. There are answers. There's on-demand training. It's worth its weight in gold, in terms of what it allows me to do.