May 2011
Beginner to intermediate
384 pages
12h 28m
English
An interesting question to investigate using the Event Study Explorer is the relationship between firm capitalization and the response to news. A reasonable prior is that smaller capitalization firms with less intensive news coverage would show greater response to extreme sentiment news events. Figure 6.13 overlays the event study charts, segmented into four capitalization groups as shown by the label “Cumulative excess return”.
The chart in Figure 6.13 conforms strongly to expectations, with the exception of negative news for the smallest capitalization group.
For positive sentiment events (upper lines) the lowest cap group shows a large response (2–3% excess returns relative to others in the sector/cap group). Note the 60-day scale in Figure 6.13. There is ample time to accumulate positions in these (apparently) under-followed stocks.
For negative sentiment events (lower lines), a similar picture is seen, with the negative excess return lines declining and the largest cap (i.e., most followed) showing the smallest effects. The next two lower capitalization classes line up in beauty contestant fashion, but the smallest cap group (under $2bn) shows anomalous behavior, essentially flat for 40 days, then slightly positive.
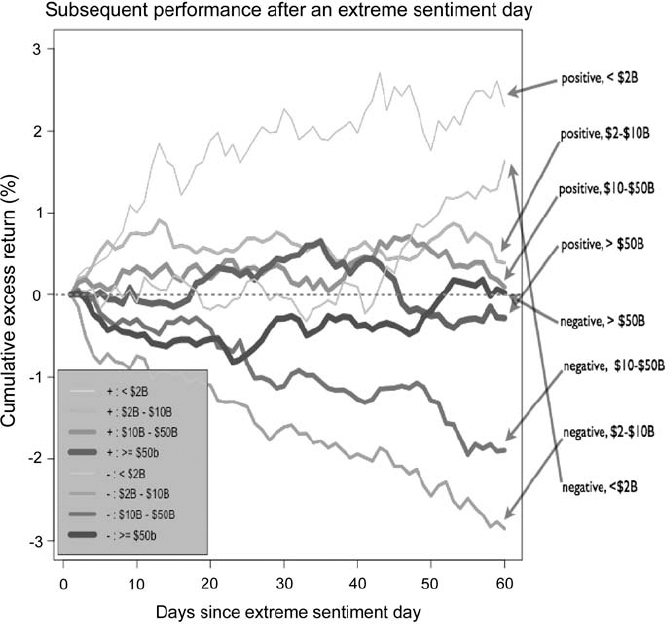
Figure 6.13. Subsequent cumulative return after an extreme sentiment day relative to sector and market capitalization ...
Read now
Unlock full access


 O’Reilly covers everything we've got, with content to help us build a world-class technology community, upgrade the capabilities and competencies of our teams, and improve overall team performance as well as their engagement.I wanted to learn C and C++, but it didn't click for me until I picked up an O'Reilly book. When I went on the O’Reilly platform, I was astonished to find all the books there, plus live events and sandboxes so you could play around with the technology.I’ve been on the O’Reilly platform for more than eight years. I use a couple of learning platforms, but I'm on O'Reilly more than anybody else. When you're there, you start learning. I'm never disappointed.I'm always learning. So when I got on to O'Reilly, I was like a kid in a candy store. There are playlists. There are answers. There's on-demand training. It's worth its weight in gold, in terms of what it allows me to do.